

MyCard - Contactless Payment
Road Dogs
- 4.0
- 121.00 Reviews
- 10.00K
- Downloads
- $17.99
- Price
Screenshots
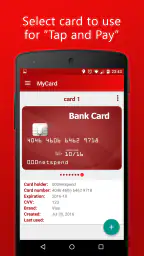
MyCard - Contactless Payment Pros and Cons
Pros
- Seamless integration with bank accounts
- Supports multiple currencies
- User-friendly interface
- Quick and secure transactions
- Low transaction fees
Cons
- Limited customer support
- Requires internet connection
- Not available in all countries
- Occasional app crashes
- Complex setup for beginners
 Analysis by All-app
I tend to notice payment friction most when I’m holding a drink, carrying shopping, or trying to keep a queue moving. A phone-based card can make that moment simpler, but only when the app, handset, and checkout terminal are all ready to cooperate. MyCard - Contactless Payment is a finance app from Road Dogs built around that tap-to-pay idea. I’d treat it as a possible alternative to reaching for a physical bank card, not as a reason to leave the card at home before checking that the setup works for me.
Where contactless payments can get stuck
The promise of paying with a phone sounds straightforward, yet a failed tap can have several causes. The terminal may not be ready, the phone may not be positioned where its NFC reader can connect, or the card and payment setup may need attention. In a busy shop, it is easy to assume the app is at fault when the problem is simply an awkward tap or a checkout that is not prepared for contactless payment.
That distinction matters because a payment app cannot make every checkout accept a phone. If the terminal does not support the payment method, repeatedly tapping the screen will not help. I would look for the contactless symbol, ask the cashier if needed, and keep a physical card available while trying a new payment setup. That small backup makes the first few outings less stressful.
There is also a practical difference between having a bank card and having it ready for phone payments. A digital wallet is only convenient if the card can be added and the payment flow is clear. Before relying on it for a time-sensitive purchase, I’d try it during a quiet stop, when I have time to check the screen and respond to any prompt rather than holding up a queue.
Making phone payments work in everyday life
The first thing I noticed about MyCard - Contactless Payment is how seamless the entire payment process is. Imagine walking into your favorite coffee shop, ordering your usual latte, and just tapping your phone to pay. No more rummaging through your bag for your wallet or dealing with the frustration of forgotten PINs. It’s like magic, but real and incredibly efficient.
Setup checks before you depend on it
Getting started is a breeze. All you need is to download the app, link your bank account or card, and you’re set. The user interface is clean and straightforward, so even if you’re not tech-savvy, you’ll find your way around pretty easily. I found the setup process intuitive, which is a big plus for those of us who prefer skipping the tech jargon.
Before treating that setup as finished, I’d check that NFC is available and enabled on the phone, since contactless payment depends on a short-range connection. The app is listed for Android devices running version 5.0 or later, but meeting that minimum alone does not guarantee that every handset has the same NFC hardware or behaves identically. If the phone has no NFC capability, this particular tap-to-pay use case is not a fit.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
I’d also take a moment to confirm that the card details have been entered correctly and that the bank card itself is active for ordinary purchases. If a setup step asks for confirmation, complete it before heading to a checkout. The useful habit here is to test one small purchase rather than assuming a successful install means the payment is ready. That separates setup trouble from a problem at the till.
MyCard costs $17.99, so I’d weigh that outlay against how often I actually want to pay by tapping my phone. Someone who already carries a wallet and only makes occasional contactless purchases may not see enough extra convenience to justify paying for another finance app. For a person who values keeping the phone as the main payment tool, the price deserves consideration alongside whether the app works with their own card and routine.
Recovering smoothly when a tap fails
One thing we can’t ignore when it comes to payment apps is security. With MyCard, your transactions are secure with their advanced encryption technology. I felt at ease knowing that my financial information was well-protected. The app also sends instant notifications for every transaction, which is great for keeping track of your spending and spotting any suspicious activity.
If a payment does not go through, I would pause rather than tap repeatedly. First, check whether the terminal has ended the attempt or is still waiting; then follow any instruction shown by the cashier or the phone. If it is clear the payment failed, use the physical card or another accepted method and investigate later. This avoids accidentally creating confusion about whether a transaction completed.
For a later check, compare the app’s transaction information with the bank’s own account view. A notification can be useful for awareness, but it should not replace checking the actual account when a purchase looks uncertain. If the terminal says the payment failed but the account shows a charge, I’d keep the receipt and contact the bank or merchant through their usual support channels rather than making a second purchase immediately.
Good payment habits still matter even when a phone is involved. I would use the phone’s normal screen lock and avoid handing an unlocked device to someone else at a checkout. Those are sensible safeguards for any device used to access financial services; an app’s security claims do not remove the need to protect the handset itself.
Cards, alternatives, and the trade-offs
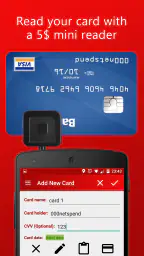
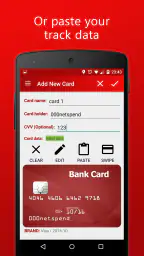
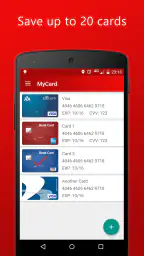
Another cool feature is the app’s ability to store multiple cards. Whether you’re using a debit card, credit card, or even a membership card, MyCard has got you covered. It’s like having a digital wallet that’s always with you. Plus, the app allows you to manage your cards, check your balance, and even view transaction history all in one place.
That kind of consolidation is most useful when I want to choose between more than one payment card without opening a physical wallet. I’d still be deliberate about which card I select before paying, especially if one is for everyday spending and another is reserved for a particular purpose. A quick check before approaching the terminal can prevent the wrong-card choice and make the checkout less hurried.
Compared with carrying a physical card, using a phone can reduce the number of things I need to pull out, but it also makes payment depend on a charged, functioning handset. A physical card is the simpler backup when the phone is unavailable or the app is not ready. Compared with a bank’s own payment option or another digital wallet, the deciding question is not which sounds more modern; it is which one supports the cards I use and works consistently on my device.
I would not assume that the multiple-card description means every kind of membership card can be used to pay at a terminal. Payment cards and loyalty or membership cards serve different purposes, and acceptance depends on the checkout’s system. I’d test the exact card and store combination I care about rather than relying on a general idea of an all-in-one wallet.
The app is marked for Everyone, which makes its age classification broad, but that does not change the need for care with financial details. I would help a less experienced user understand which card is being used and how to check a purchase, rather than treating the age label as a substitute for guidance.
When the app may not be the cause
So, how does it fare in real life? I tested it at different places - cafes, grocery stores, and even online shopping. The response time was quick, and I didn’t face any hiccups during the payments. It’s like having a trusty sidekick that never lets you down. Plus, the app’s compatibility with various payment systems makes it super versatile.
A realistic routine might be a quick grocery stop after work: I choose the card before reaching the counter, keep the phone accessible, and check the terminal before tapping. If it accepts contactless payment, I can complete the purchase without opening my wallet. If it does not, I use my backup card and move on. That is where phone payment feels useful to me: it makes a familiar task a little smoother without requiring the whole errand to depend on one method.
When a tap fails in one shop but works elsewhere, I would first suspect differences in the terminal or checkout process rather than conclude that the app has stopped working. If it fails repeatedly across places, I’d review NFC and card setup, restart the phone if appropriate, and check whether the card itself works through its normal channel. These are safe first checks; they do not require changing security settings or sharing financial information with anyone.
MyCard was released on Mar 22, 2016, and its current version is 1.21. The app has a 4.0 average from around 285 ratings, alongside 121 written reviews, and has passed 10,000 installs. Those figures give a sense of its presence, but they cannot tell me whether it will work with a particular phone, card, or shop. My own decision would rest on a cautious test with the setup I actually plan to use.
Who is likely to benefit—and who should pass
I can see this being useful for someone who already pays by card, has an NFC-capable Android phone, and wants a phone-based option for everyday purchases. It is especially appealing if carrying a wallet is inconvenient and the person is willing to keep a backup card nearby until the payment routine feels dependable. The multiple-card approach may also suit someone who regularly chooses among different cards and values having them together.
I would skip it if I rarely use contactless payments, do not want to pay for an extra finance app, or prefer the straightforward reliability of carrying a bank card. It is also a poor match for a phone without NFC, or for anyone who wants every shop and every card to work without checking compatibility. If the bank’s existing option already handles the same need comfortably, switching adds little unless MyCard offers a practical advantage in that person’s own routine.
Road Dogs presents MyCard as a focused finance tool rather than a general budgeting companion. That focus can be a strength for someone who wants payment access, card handling, and transaction visibility in one place. It should not be mistaken for a replacement for broader bank services: when I need help with a declined card, a disputed charge, or account access, the bank remains the relevant point of contact.
My practical verdict
Overall, MyCard - Contactless Payment shines in making payments easier and more secure. If you’re looking for a reliable and efficient way to handle your transactions, give it a whirl. Who knows, it might just become your favorite app too!
My recommendation is more measured: I’d try it only after checking the phone’s NFC capability, confirming the card setup, and making a low-pressure test purchase with a physical card still available. If that works smoothly and the phone-based workflow genuinely saves effort, the app could earn a place in an everyday routine. If setup or acceptance proves inconsistent, using a regular bank card—or a payment method already supported by the bank—is the more sensible choice.
Frequently Asked Questions
What is MyCard - Contactless Payment used for?
MyCard - Contactless Payment is a mobile app that enables users to make secure contactless payments directly from their smartphone. By linking your credit or debit cards to the app, you can easily pay at stores, restaurants, and other services without needing to carry physical cards. It's a convenient solution for modern, cashless transactions.
Is MyCard - Contactless Payment secure to use?
Yes, MyCard - Contactless Payment is designed with security as a top priority. It employs advanced encryption technologies to protect your card information and transaction details. Additionally, users have the option to enable biometric authentication, such as fingerprint or facial recognition, to further safeguard their accounts and prevent unauthorized access.
Can I use MyCard - Contactless Payment internationally?
MyCard - Contactless Payment can be used internationally, provided that the merchant accepts contactless payments. It's crucial to ensure your linked cards are enabled for international transactions. Be aware of potential foreign transaction fees that may be applied by your card issuer when using the app abroad.
What types of cards can I link to MyCard - Contactless Payment?
Users can link a wide range of credit and debit cards from major financial institutions to MyCard - Contactless Payment. This includes cards from Visa, MasterCard, American Express, and Discover. Always check with your card issuer to confirm compatibility with contactless payment services to ensure a smooth setup and usage experience.
How do I troubleshoot issues with MyCard - Contactless Payment?
If you encounter issues with MyCard - Contactless Payment, start by checking your internet connection and ensuring that the app is updated to the latest version. For persistent problems, the app features a robust support section with FAQs and troubleshooting tips. You can also contact customer support directly through the app for personalized assistance.


